Tag: UK Property Investment

  • Sylvest Featured Across Leading UK Media Platforms: What It Means for Deal Sourcers & Property Investors

    Sylvest Featured Across Leading UK Media Platforms: What It Means for Deal Sourcers & Property Investors

    Building a trusted name in the UK property sector takes more than creating a platform. It requires visibility, credibility and a clear purpose.

    For Sylvest, being featured across a growing number of UK media platforms represents an important milestone in the development of its property introduction marketplace. The coverage has helped put the Sylvest name in front of audiences across different parts of the UK, while bringing greater attention to the problem the platform was created to address.

    Sylvest is built around a concept: connecting Deal Sourcers with Property Investors through a more structured marketplace for property opportunities.

    Sylvest’s Growing Media Presence

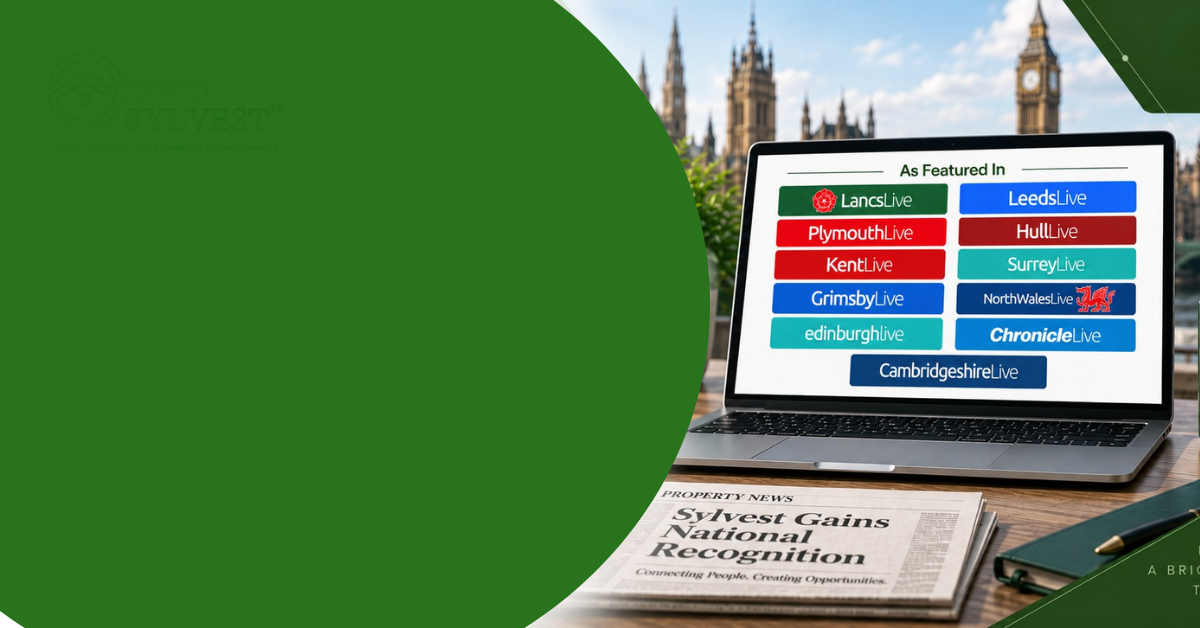
    Sylvest has been featured across established regional UK publications, including:

    The breadth of these publications is particularly relevant to a business operating across the UK property market. Rather than visibility being limited to one city or region, Sylvest is reaching audiences across different parts of the country.

    For an emerging platform, this type of exposure can help introduce the brand to people who may not previously have been aware of it.

    However, media coverage is only one part of building a business. For Sylvest, the more important objective is what happens after someone discovers the platform.

    Why Sylvest Was Created

    The story behind Sylvest comes from a real problem experienced within the property industry.

    After moving into property, Sylvest founder Lisa Mortie experienced the challenges of sourcing quality opportunities while struggling to gain access to genuine, active investors. At the same time, the investor side presented its own difficulty: finding credible property opportunities and reliable sources was not always straightforward.

    The experience highlighted a gap between the two sides of the market.

    That became the foundation for Sylvest, with the aim of creating a dedicated marketplace where Deal Sourcers can present opportunities and Property Investors can discover deals that may match their requirements.

    The platform is therefore not simply another place to advertise property. Its focus is on the connection between the person sourcing the opportunity and the person looking for one.

    What the Media Exposure Means for Deal Sourcers

    For Deal Sourcers, visibility matters because sourcing a property is only part of the process.

    A suitable opportunity still needs to reach an appropriate buyer.

    Many sourcers build investor relationships through networking, referrals, social media and personal contacts. These channels can be valuable, but they can also leave a sourcer dependent on the size and activity of their existing network.

    Sylvest provides another route.

    Deal Sourcers can list their property deals on the platform, where listings go through a review process before publication. Investors can then discover available opportunities and decide whether they want to proceed towards an introduction.

    Greater awareness of Sylvest can therefore help more sourcers discover a platform specifically designed around the challenge of connecting property opportunities with potential buyers.

    For a Deal Sourcer, that can mean having another channel through which a suitable deal can be presented to a relevant audience.

    What It Means for Property Investors

    The value of the marketplace works in both directions.

    Property Investors are often looking for opportunities that match specific criteria, whether that involves location, purchase price, investment strategy or property type.

    Sylvest allows investors to browse listed opportunities and, when they find a deal of interest, proceed towards an introduction with the relevant sourcer.

    This gives investors another route to discovering opportunities, including off-market deals that may not appear through conventional property portals.

    Sylvest also makes an important distinction around due diligence. The platform facilitates introductions, but investors remain responsible for carrying out their own independent legal, financial and property checks before deciding whether to proceed.

    That distinction is important because visibility should never be confused with a guarantee of an investment opportunity.

    From Media Recognition to Market Awareness

    The significance of Sylvest’s media exposure goes beyond the number of publications carrying its name.

    Each feature creates another opportunity for someone to discover the business, understand its purpose and potentially explore the marketplace.

    This is particularly useful for an emerging property technology company because awareness is closely connected to marketplace growth.

    More sourcers can bring more opportunities.

    More investors can create a larger potential audience for those opportunities.

    And as both sides become more active, the platform has greater potential to facilitate relevant introductions.

    That is the type of ecosystem Sylvest is working towards.

    Building a More Structured Connection

    The UK property market contains a wide variety of investors and sourcing businesses. Their requirements are not identical, and a deal that works for one investor may be completely unsuitable for another.

    This makes relevance important.

    Sylvest’s marketplace is designed around helping investors discover opportunities while giving sourcers a dedicated place to present their deals. Its stated mission is to create more seamless connections between the two sides and provide access to investment opportunities through a structured marketplace.

    That structure can be particularly valuable when the alternative is relying entirely on scattered conversations, social media posts and informal introductions.

    What Comes Next for Sylvest?

    The media coverage is an encouraging milestone, but Sylvest’s longer-term objective goes beyond recognition.

    The company is continuing to develop its marketplace, verification approach, educational resources and relationships within the property industry. Its wider ambition is to build a recognised destination where investment opportunities and credible property professionals can connect more efficiently.

    That means continuing to focus on the fundamentals: clear information, transparency, relevant introductions and a better experience for both sides of the marketplace.

    Media exposure can help more people discover Sylvest. The platform itself then has to deliver the value that keeps them engaged.

    A Significant Step for Sylvest

    Being featured across WalesOnline, ChronicleLive, Hull Live, Get Surrey, Daily Post, Kent Live, Cornwall Live, Plymouth Herald, Grimsby Live, Leeds Live, Cambridge News, Edinburgh Live and LancsLive marks an important stage in Sylvest’s growth.

    For Deal Sourcers, it brings greater awareness of a platform designed to help them present property opportunities to a relevant audience.

    For Property Investors, it introduces another marketplace where they can discover potential deals and connect with the people sourcing them.

    The next stage is not simply about reaching more people. It is about turning that awareness into meaningful connections and helping the right opportunities reach the right people.

    Explore Sylvest

    If you are a Deal Sourcer with property opportunities to present or a Property Investor looking for your next potential deal, Sylvest provides a dedicated marketplace where both sides can connect.

    Explore Sylvest and discover a more structured way to connect property opportunities with investors.
  • The Future of UK Property Investment: Sylvest Featured Across Leading Media Platforms

    The Future of UK Property Investment: Sylvest Featured Across Leading Media Platforms

    Building a trusted name in the UK property sector takes more than creating a platform. It requires visibility, credibility and the confidence of the people who use it.

    For Sylvest, being featured across leading UK media platforms represents an important step in that journey.

    The coverage has placed Sylvest in front of audiences across the UK, spanning publications including WalesOnline, ChronicleLive, Hull Live, Get Surrey, Daily Post, Kent Live, Cornwall Live, Plymouth Herald, Grimsby Live, Leeds Live, Cambridge News, Edinburgh Live and LancsLive.

    For a growing property investment marketplace, this kind of exposure can help more people discover what Sylvest is building and, more importantly, understand why a more structured approach to property introductions matters.

    Sylvest’s Place in the UK Property Market

    Sylvest was created to address a familiar problem within property investment: the difficulty of efficiently connecting quality property opportunities with suitable investors.

    The platform brings Deal Sourcers and property investors together in one marketplace, allowing sourcers to showcase investment opportunities while investors can browse deals that may fit their investment strategy. Sylvest describes its purpose as creating a simpler and more transparent way for both sides to connect.

    This is particularly relevant in a market where many property opportunities have traditionally been shared through personal networks, social media groups and informal introductions.

    Sylvest aims to provide another route.

    Rather than relying entirely on who happens to be in a Deal Sourcer’s personal network, the platform gives sourcers a dedicated place to present their opportunities to an audience interested in property investment.

    Featured Across Leading UK Media Platforms

    Sylvest’s recent exposure extends across a broad collection of regional UK publications.

    These include:

    The scale and geographical spread of these publications provide an opportunity for Sylvest to reach audiences well beyond a single local property market.

    For a platform focused on UK property, that wider visibility is particularly valuable. Property investment is not confined to one region, and neither are the investors and Deal Sourcers looking for opportunities.

    At the same time, the media coverage should be viewed as part of Sylvest’s growing visibility rather than as a substitute for the trust that ultimately comes from how the platform operates.

    Why Visibility Matters for Deal Sourcers

    For Deal Sourcers, one of the biggest challenges is often not finding a property. It is finding the right audience for that property.

    A sourcer can have a strong opportunity, but if the deal is only circulated among a small group of personal contacts, its potential audience remains limited.

    Greater awareness of Sylvest can help address that problem by introducing more Deal Sourcers to a dedicated marketplace built around property opportunities.

    Sylvest allows sourcers to list their deals, with listings reviewed before publication. The platform also provides a process for connecting interested investors with the sourcer once an investor decides to proceed.

    For a Deal Sourcer, the benefit is not simply another place to advertise. It is another channel through which an investment opportunity can reach potential buyers.

    What Media Recognition Means for Investors

    The value of increased visibility works both ways.

    Investors need access to opportunities, but they also need enough information to decide whether a deal deserves further investigation.

    Sylvest’s model is centred on bringing investment opportunities and investor requirements together. Investors can browse listed deals and, when they find an opportunity of interest, proceed towards an introduction with the Deal Sourcer.

    The platform also states that listed opportunities undergo a review process before publication. However, Sylvest makes clear that investors should still carry out their own due diligence before proceeding with any investment.

    That distinction is important.

    A platform can make the process of discovering opportunities and making introductions more structured, but the final investment decision remains with the investor.

    Building Trust Through Transparency

    Media exposure is valuable, but for Sylvest, the bigger objective is building a property marketplace where both sides know what to expect.

    The company’s model focuses on transparency, efficiency and direct connections between Deal Sourcers and investors. Its platform allows sourcers to retain ownership of their listings while Sylvest facilitates introductions between the two parties.

    That approach is closely connected to the story behind Sylvest.

    The platform was created after its founder experienced the difficulties of sourcing property deals without reliable access to a genuine investor network. That experience led to the idea of creating a more structured marketplace where Deal Sourcers could showcase opportunities and investors could discover them in one place.

    Looking Ahead

    Being featured across leading UK media platforms is an encouraging milestone for Sylvest, but it is only part of a much bigger journey.

    The UK property market contains investors with different strategies, budgets and objectives, alongside Deal Sourcers working across a wide range of locations and property types.

    The opportunity for Sylvest is to make those connections easier to establish.

    As awareness of the platform grows, so does the potential to bring more investors and Deal Sourcers into the same marketplace. That can create a stronger environment for discovering investment opportunities, developing professional relationships and turning suitable introductions into completed transactions.

    For Deal Sourcers, the message is straightforward: having a good deal is important, but having access to the right audience can be just as important.

    For investors, the opportunity is equally clear: finding suitable property deals can become easier when the people sourcing those opportunities and the people looking for them have a dedicated place to connect.

    A Growing Platform With a Clear Purpose

    Sylvest’s appearance across publications such as WalesOnline, ChronicleLive, Hull Live, Get Surrey, Daily Post and other regional UK media platforms marks an important moment in the platform’s development.

    But the real measure of Sylvest will continue to be the connections it creates.

    For Deal Sourcers, that means greater visibility for quality property opportunities. For investors, it means another route to discovering potential deals and connecting directly with the people who source them.

    Want to be part of the growing Sylvest property investment marketplace?

    List your property deal with Sylvest or explore opportunities from Deal Sourcers across the UK.

  • What Is Social Housing Investment? The Honest UK Guide

    What Is Social Housing Investment? The Honest UK Guide

    Social housing investment is one of the most misrepresented strategies in UK property. On one side, it gets oversold as guaranteed income with zero effort. On the other, it gets dismissed as too complicated, low-margin, or ethically problematic. Neither description is accurate.

    This guide gives you the actual model, including how social housing investment works, what it pays, what can go wrong, and who it genuinely suits. No spin in either direction.

    Table of Contents

    • What Social Housing Investment Actually Is
    • How Social Housing Investment Works
    • The Main Types of Social Housing Deal
    • The Honest Case For Social Housing Investment
    • The Honest Case Against Social Housing Investment
    • Who Social Housing Investment Suits
    • How to Find Social Housing Deals
    • The Bottom Line

    Quick Summary

    Takeaway Explanation
    Social housing offers stable, predictable income. Many arrangements provide fixed monthly payments through a housing provider, reducing exposure to tenant vacancies and rent arrears.
    Guaranteed rent is not government-backed. Payments depend on the financial strength and reliability of the housing provider, not the government itself.
    There are multiple social housing models. Investors can work through local authorities, housing associations, supported living providers, or specialist social housing companies.
    Lower yield is the primary trade-off. Social housing often generates lower rental income compared to open-market lets in exchange for greater stability and reduced management.
    Provider due diligence is essential. The quality and financial health of the housing provider significantly impact investment performance and risk.
    Management responsibilities are reduced. Housing providers typically handle tenant placement, day-to-day management, and ongoing tenancy administration.
    Maintenance costs may be higher. Some properties, especially supported living accommodation, require more frequent repairs or specialist adaptations.
    Social housing suits long-term investors. It works best for investors prioritising dependable cash flow and lower operational involvement rather than maximum returns.
    Property standards must be met. Housing providers often require minimum EPC ratings, good property condition, and compliance with specific requirements.
    Location remains critical. Demand is strongest in areas with established social housing needs, making local market knowledge important.

    What Social Housing Investment Actually Is

    Social housing investment involves making a privately owned property available to tenants referred or managed by a local authority, housing association, or registered charity.

    The investor is still the landlord. The property is still privately owned. However, the tenant selection and management route are handled by the housing provider rather than a standard letting agent or the landlord directly.

    There are several distinct models within this category. Therefore, they are not all the same. Conflating them is where much of the confusion about this strategy starts.

    How Social Housing Investment Works

    The most common arrangement is a lease between the property owner and a housing provider. This can be a local authority, a registered housing association, or a specialist social housing company.

    Typically, the housing provider takes on management of the property, places tenants, and pays the landlord a fixed monthly amount regardless of whether the property is occupied. This fixed payment is where the term ‘guaranteed rent’ comes from.

    However, it is not guaranteed by the government. Instead, the payment is guaranteed by the housing provider for the duration of the lease. As a result, the reliability of that payment depends entirely on the financial strength and track record of the organisation you are leasing to. This distinction matters.

    The Main Types of Social Housing Deal

    Within social housing investment, there are four distinct routes:

    • Direct local authority lease: Your property is leased directly to the council. This can offer high security and council-backed payments, although the yield may be lower. Demand for this arrangement exists in many areas, but waiting times vary.
    • Housing association lease: The structure is similar, but the arrangement is through a registered housing association. Terms vary significantly between providers. Therefore, due diligence on the specific housing association is essential.
    • Supported living: These properties are used for tenants with additional needs and are managed through specialist organisations. Although yields can be higher, the property may need to meet specific requirements relating to type, location, layout, or adaptations.
    • Social housing company lease: Private companies operate as intermediaries between landlords and social tenants. Quality varies enormously. Some are well-run and financially sound, while others are not. For that reason, vetting the company before signing is critical.

    “The yield in social housing is lower than open market. What you are buying is certainty of income and the removal of void risk and management cost.”

    The Honest Case For Social Housing Investment

    The primary appeal is income stability. In many arrangements, investors can reduce exposure to void periods, tenant-finding costs, rent arrears, and day-to-day management. For investors who want predictable monthly income rather than maximum yield, this can be a genuine structural advantage.

    Furthermore, lease lengths of three to five years can reduce the administrative burden significantly compared to standard tenancies.

    For investors holding larger portfolios, social housing can function as a stable income floor. In other words, predictable cash flow from one part of the portfolio can sit alongside properties that deliver higher but more variable returns.

    The Honest Case Against Social Housing Investment

    Yield is the first trade-off. Expect to receive 10 to 20 per cent below open market rent, and sometimes more. Therefore, if your investment plan depends on maximising yield from each property, social housing may not be the right strategy.

    Provider risk is also real. If a social housing company fails mid-lease, you could be left with arrears owed, a legally complex situation, and a property that needs to be re-let quickly. This risk is not theoretical.

    Maintenance costs can also be higher, particularly in supported living arrangements. Properties in this sector typically require more frequent repair and may need specific adaptations. Consequently, you should build a realistic maintenance allowance into your projections rather than relying on the deal sourcer’s default figures.

    In addition, most housing providers require the property to meet a minimum standard before they will take it on. EPC rating, general condition, and sometimes specific layout requirements can all apply.

    Who Social Housing Investment Suits

    Social housing investment can suit investors who want stable, long-term income as part of a wider portfolio. It can also work for people who are prepared to accept a lower yield in exchange for greater certainty and reduced day-to-day management.

    However, it is not a good fit for investors who need maximum return per property, plan to sell within two years, or need flexibility over the asset during the lease period.

    Location matters considerably, too. The strongest social housing demand is concentrated in specific areas. Therefore, a deal sourcer with genuine local knowledge is worth talking to before you commit to any particular property or provider.

    How to Find Social Housing Deals

    Social housing investment opportunities rarely appear on Rightmove or Zoopla. Instead, they often come through specialist deal sourcers, direct relationships with housing associations, or platforms where deal sourcers list deals by strategy.

    On Sylvest, deal sourcers list social housing opportunities directly on the platform. You can filter by strategy, review the deal pack, and ask the deal sourcer specific questions about the provider and the lease terms before making any decision.

    Before committing to a deal, it is also worth checking relevant guidance and information from authoritative UK sources, such as GOV.UK and HM Land Registry, alongside the information supplied by the deal sourcer and housing provider. This gives you additional context when assessing the property and the proposed arrangement.

    The Bottom Line

    Social housing investment is neither a guaranteed-income shortcut nor an inherently poor investment strategy. Instead, it is a different way of structuring a property investment around income stability and reduced management involvement.

    The trade-off is straightforward: you may accept a lower rent or yield in return for greater predictability. At the same time, provider strength, lease terms, property standards, maintenance requirements, and location still need careful assessment.

    For the right investor, that balance can make social housing a useful part of a wider UK property portfolio. The key is to understand exactly what is being offered before you commit.

  • HMO vs Buy-to-Let vs Serviced Accommodation: Which Strategy Wins in 2026?

    HMO vs Buy-to-Let vs Serviced Accommodation: Which Strategy Wins in 2026?

    HMO vs Buy-to-Let vs Serviced Accommodation is a comparison that comes up in almost every conversation about UK property investment. Three strategies. One asset class. Completely different outcomes depending on who is holding the property.

    Most people pick one based on what they have heard works rather than what actually fits their budget, location and available time. This guide breaks all three down so you can compare the numbers, management demands, risks and potential returns before deciding which strategy fits your investment goals.

    Table of Contents

    • HMO vs Buy-to-Let vs Serviced Accommodation: Understanding the Differences
    • The Quick Definitions
    • Comparing the Numbers That Matter
    • HMO: The Case For and Against
    • Buy-to-Let: The Simpler Route
    • Serviced Accommodation: High Ceiling, High Variance
    • Finding the Right Deal for Your Strategy
    • The Bottom Line

    Quick Summary

    Takeaway Explanation
    HMO typically delivers the strongest consistent yields. Multiple tenants create multiple income streams, helping reduce the impact of vacancies and increasing overall rental income potential.
    Buy-to-Let offers simplicity and stability. With one property and one tenant, BTL is easier to finance, manage, and scale for many investors.
    Serviced Accommodation can generate the highest gross returns. In strong locations, nightly rates can significantly outperform traditional rentals, although income can fluctuate throughout the year.
    Each strategy has different management demands. HMO and SA require more active involvement, while BTL is generally the least operationally intensive option.
    Financing and regulations vary by strategy. HMOs often require specialist mortgages and licensing, while SA may face local council restrictions and additional compliance requirements.
    Location plays a major role in performance. Student towns and city centres often suit HMOs, while SA performs best near tourism, healthcare, business, and travel hubs.
    Gross yield does not tell the full story. Investors should account for management, maintenance, cleaning, platform fees, voids, and financing costs before comparing opportunities.
    The best strategy depends on your goals. Budget, risk tolerance, available time, and desired level of involvement should guide the decision more than headline yield figures.

    HMO vs Buy-to-Let vs Serviced Accommodation: Understanding the Differences

    HMO, Buy-to-Let and Serviced Accommodation all generate rental income, but they do so in very different ways. An HMO generally relies on multiple tenants within one property, while Buy-to-Let normally involves a single tenancy. Serviced Accommodation, meanwhile, operates more like short-let hospitality, with guests paying for individual nights or short stays.

    As a result, the same property can produce very different financial outcomes depending on the strategy used. However, higher potential income usually comes with greater management requirements, running costs or regulatory considerations.

    The Quick Definitions

    HMO stands for Houses in Multiple Occupation. One property, multiple tenants and multiple separate rents. A five-bedroom house rented to five professionals can therefore generate five separate income streams rather than one.

    Buy-to-Let is the most familiar model: one property, one tenancy and one monthly payment. It is generally simpler to manage, although the investor remains dependent on a single rental income stream.

    Serviced Accommodation sits closer to short-let hospitality. The property is furnished and managed on a per-night basis. Yields can be significantly higher, but income is seasonal and running costs are also higher.

    Comparing the Numbers That Matter

    Here is how the three strategies compare across some of the factors that can affect your returns:

    Factor HMO Buy-to-Let Serviced Accommodation
    Average gross yield 7-12% 4-6% 10-20%+*
    Day-to-day management High Low to medium Medium to high
    Licensing required Yes, depending on property and local rules Minimal Varies by council and property
    Mortgage type Specialist HMO Standard BTL Commercial or bridge
    Income pattern Steady, multi-tenant Steady, one tenant Variable, seasonal
    Best-fit investor Experienced, near city Beginner to mid-level Near tourism or travel hubs

    *SA yields are peak-season figures. Net returns after platform fees, cleaning and furnishing can be significantly below gross returns.

    The figures above should be treated as broad comparisons rather than guaranteed market averages. Actual performance depends on purchase price, location, occupancy, financing, operating costs and the specific property.

    HMO: The Case For and Against

    HMO can produce the highest consistent yield of the three strategies. Multiple rent streams from a single property mean that one vacant room does not necessarily eliminate the property’s entire rental income. In student towns, city centres and commuter belt areas with strong professional demand, HMO can perform well.

    However, the trade-off is complexity. Many HMOs require a licence, while Article 4 areas can introduce additional planning considerations. You may also need a specialist HMO mortgage rather than a standard BTL product.

    Day-to-day management is heavier, too. More tenants can mean more maintenance, greater tenant turnover and additional administration. Therefore, HMO suits an investor who is either hands-on by nature or has a letting agent who works specifically with multi-let properties.

    It is not necessarily the right starting point for every investor.

    Buy-to-Let: The Simpler Route

    The appeal of Buy-to-Let is straightforwardness. Standard residential mortgages, one tenant relationship and one monthly payment make the model easier to understand and, in many cases, easier to manage.

    For investors building a portfolio across different cities, BTL can also scale more cleanly than HMO. The operational workload is generally lower, particularly when a managing agent is used.

    The ceiling is the issue. Four to six per cent gross is the average range used in this comparison, and after mortgage costs, maintenance and void periods, the actual return can be considerably lower.

    On the open market, well-priced BTL properties can attract multiple buyers quickly. That is exactly where off-market sourcing can earn its value: access to motivated sellers before the general market knows about the opportunity.

    Serviced Accommodation: High Ceiling, High Variance

    Serviced Accommodation attracts attention because the headline yield numbers can look extraordinary. Ten to 20 per cent gross can be achievable in strong locations. In the right postcode, near a hospital, university, conference centre or tourist destination, short-let demand can support attractive nightly rates.

    However, SA is the most operationally intensive of the three. There are furnishing costs upfront, cleaning between bookings and platform fees from services such as Airbnb or Booking.com. Some areas may also have specific planning, licensing or local authority requirements.

    Seasonality is another major consideration. A strong August does not guarantee a full February. Consequently, investors need to model occupancy and operating costs across the entire year rather than relying on peak-season figures.

    SA can suit investors near genuine demand generators who are comfortable with variable monthly income and active management. Alternatively, a reliable co-host or specialist operator can reduce the day-to-day workload.

    “Yield figures tell you the ceiling. Net return tells you the truth. Factor in every cost before you compare.”

    Finding the Right Deal for Your Strategy

    Picking a strategy is one decision. Finding the right deal for that strategy is a separate one, and it is where many investors lose time.

    On Sylvest, investors can browse property opportunities by strategy. HMO listings can come from deal sourcers with information on licensing, conversion viability and local rental levels. BTL listings can include yield projections and deal sourcer notes. SA deals can highlight the location and demand factors relevant to short-let performance.

    The important point is that the strategy should come before the property. A property that works well as a BTL may not work as an HMO, while a property that looks attractive for SA may struggle outside its peak demand periods.

    You choose the strategy. Then assess whether the deal actually supports it.

    The Bottom Line

    There is no single winner when comparing HMO vs Buy-to-Let vs Serviced Accommodation. Each strategy offers a different balance between income potential, management requirements, risk and complexity.

    HMO can offer strong and relatively consistent rental income, but it comes with greater management and compliance requirements. Buy-to-Let is generally simpler and easier to operate, although the income ceiling is often lower. Serviced Accommodation can produce higher gross revenue, but it also brings greater variability, operating costs and management demands.

    Ultimately, the best strategy is the one that fits your budget, location, experience and appetite for involvement. Headline yield should be part of the decision, but it should never be the only number you look at.

  • What Is Off-Market Property Investing? The Complete UK Guide

    What Is Off-Market Property Investing? The Complete UK Guide

    Off-market property investing is a popular strategy among UK investors looking for opportunities that are not publicly advertised on the major property portals. Instead of competing with every buyer searching Rightmove or Zoopla, investors can access properties through private networks, deal sourcers, packagers, and direct vendor relationships.

    For some investors, the attraction is simple: less competition, greater access to motivated sellers, and the potential to negotiate better terms. However, off-market does not automatically mean below market value or better returns. The quality of the deal still depends on the property, price, location, strategy and due diligence.

    Table of Contents

    • What Is an Off-Market Property Deal?
    • Types of Off-Market Property Deals in the UK
    • Why Experienced Investors Prefer Off-Market Opportunities
    • How Deal Sourcers Support Off-Market Investors
    • How Sylvest Makes Off-Market Property Investing Accessible
    • The Bottom Line

    Quick Summary

    Takeaway Explanation
    Off-market properties are not publicly advertised. These properties are sold through private networks, deal sourcers, packagers, or direct vendor connections rather than listing portals.
    Investors can face less competition. Fewer buyers may be aware of off-market opportunities, potentially creating more room for negotiation.
    Multiple off-market deal types exist. Common opportunities include BMV properties, distressed sales, pre-sale exclusives, packaged deals, and direct vendor transactions.
    Deal sourcers help identify opportunities. Sourcers leverage their networks to find and present investment properties before they reach the open market.
    Due diligence remains essential. Investors should always review financials, market conditions, property details and legal information before proceeding with any investment.
    Sylvest provides access to off-market opportunities. The platform connects investors with deal sourcers and allows users to search opportunities based on their investment strategy.
    Off-market investing can improve buying opportunities. Better pricing, reduced competition and stronger yields can potentially improve investment outcomes, although none are guaranteed.

    What Is an Off-Market Property Deal?

    An off-market property is generally a property being offered for sale without being publicly advertised through the usual property portals. You may not find it on Rightmove, Zoopla or an estate agent’s public listings.

    Instead, these properties can change hands through private networks, deal sourcers, packagers or direct vendor connections. Sellers may choose this route for several reasons, including speed, privacy or the desire to avoid a lengthy public marketing process.

    For example, a landlord selling a portfolio quietly, an executor dealing with an inherited property, or a motivated seller who needs to move quickly may choose to explore private buyers before going to the open market.

    Off-market does not mean inferior. It simply means the opportunity is not being openly marketed to the wider market. For the right buyer, that difference can create an opportunity to negotiate before wider competition appears.

    “Off-market doesn’t mean hidden from everyone. It means hidden from the crowd, which is exactly where serious investors want to be.”

    Types of Off-Market Property Deals in the UK

    Off-market property investing covers several different types of opportunity. In practice, you may come across the following:

    • Below Market Value (BMV): Properties offered below an estimated current market value, often because the seller prioritises a quick sale. These deals are highly sought after, but establishing the genuine market value is essential.
    • Distressed Sales: Properties where the seller is motivated to complete quickly. However, investors should understand why the seller is moving quickly and carry out appropriate due diligence before proceeding.
    • Pre-Sale Exclusives: Opportunities a deal sourcer has secured before the property reaches the wider market. This can give investors earlier access to a potential deal.
    • Sourcer-Packaged Deals: The deal sourcer provides analysis alongside the property, which may include yield projections, planning information, comparable rents and a due diligence summary.
    • Direct Vendor Sales: The investor negotiates directly with the property owner without a deal sourcer acting as an intermediary. This can reduce sourcing costs, although the investor may have to handle more of the research and negotiation themselves.

    Why Experienced Investors Prefer Off-Market Property Opportunities

    The short version is simple: less competition, potential pricing flexibility and earlier access.

    When a property reaches Rightmove or another major portal, it becomes visible to a large pool of potential buyers. Competitive offers can follow, particularly when a property is well priced. By contrast, an off-market opportunity may initially be presented to only a smaller group of investors.

    That can change the negotiation dynamic. However, less competition does not automatically mean a cheaper property. Investors still need to establish whether the asking price represents good value.

    Factor On-Market Off-Market via Sylvest
    Buyer competition Potentially very high Potentially lower
    Price flexibility Often influenced by wider market demand May provide more room for negotiation
    Access to opportunities Publicly available Through private networks and deal sourcers
    Yield potential Depends on market pricing Can be stronger on suitable deals
    Due diligence support Depends on the transaction Deal sourcers may provide supporting analysis

    These differences can become meaningful over time. An investor who consistently finds suitable properties at sensible prices may achieve better outcomes than someone relying entirely on publicly advertised opportunities.

    Nevertheless, the investment fundamentals still matter. A property does not become a good investment simply because it is off-market.

    How Deal Sourcers Support Off-Market Property Investors

    A deal sourcer spends their time finding investment properties on behalf of investors. They can build relationships with estate agents, solicitors, developers and private vendors, giving them access to opportunities that may not yet be publicly advertised.

    When a suitable match is made, the deal sourcer may earn a sourcing or finder’s fee from the investor in exchange for identifying the opportunity and saving the investor time.

    Deal packagers may go further by providing financial projections, planning information, yield analysis and an investment case alongside the property itself. For investors who value convenience and structured information, this additional work can make the process more efficient.

    However, one principle remains important regardless of who presents the opportunity: you still need to conduct your own due diligence.

    A good deal sourcer can make the process easier. They do not make independent verification optional.

    For example, investors should investigate the property’s ownership, title and other available information as part of their wider checks. HM Land Registry provides access to registered property information in England and Wales, including title registers, title plans and ownership information.

    How Sylvest Makes Off-Market Property Investing Accessible

    Until recently, accessing off-market property in the UK often depended heavily on knowing the right people and building private networks.

    Sylvest provides another route.

    On Sylvest, deal sourcers can list investment opportunities directly on the platform. Investors can browse by strategy, including HMO, Buy-to-Let, Serviced Accommodation, BMV, Social Housing and more, then connect directly with the deal sourcer behind each opportunity.

    The platform also works in reverse. Investors can post a Deals Wanted listing covering their preferred location, budget, strategy and deal type. Deal sourcers with a suitable opportunity can then respond.

    This two-way model creates a more structured way for investors and deal sourcers to connect, rather than relying entirely on informal Facebook groups and private networks.

    Even with a structured platform, however, investors should still verify the information provided and obtain appropriate professional advice before committing to a transaction. GOV.UK guidance also recommends using appropriate legal and professional support when buying property, including legal representatives and surveyors where required.

    The Bottom Line

    Off-market property investing is not a strategy reserved for investors with industry contacts built over decades. It is a legitimate route to accessing property opportunities that may not be publicly advertised.

    The potential advantages are clear: less competition, earlier access and the possibility of negotiating directly with motivated sellers. However, none of these factors guarantees a profitable investment.

    The fundamentals still matter. Investors should assess the purchase price, location, rental demand, financing, expected returns, legal position and condition of the property before proceeding.

    Sylvest brings deal sourcers and property investors together in one platform, making it easier to discover opportunities and start conversations around potential investments.

    The best off-market deal is not simply the one that was never advertised. It is the one that still makes financial and strategic sense after proper due diligence.

  • Investing in UK Property from Abroad?: A Practical Guide

    Investing in UK Property from Abroad?: A Practical Guide

    Investing in UK property from abroad is increasingly accessible for overseas investors. The UK offers an established property market, a wide range of investment strategies and strong demand across many rental markets. However, investing from another country also creates practical challenges that UK-based investors do not face.

    The biggest challenge is usually not whether you can buy a property. Instead, it is knowing where to start, choosing the right strategy, understanding the additional costs and building a reliable team that can manage the process locally.

    This guide explains how investing in UK property from abroad works, which strategies are more suitable for remote investors, what you need before investing and how deal sourcers can help.

    Table of Contents

    • Why Overseas Investors Choose UK Property
    • Can Overseas Investors Buy UK Property?
    • Which Strategies Work Best for Investing in UK Property from Abroad?
    • What You Need Before Investing in UK Property from Abroad
    • Understanding Currency and Transfer Costs
    • How Deal Sourcers Reduce the Complexity
    • How Sylvest Supports Overseas Investors
    • The Bottom Line

    Quick Summary

    Takeaway Explanation
    Overseas investors can buy UK property. Overseas investors can purchase UK property, although financing, tax and transaction requirements can differ from those faced by UK residents.
    Specialist support is important. Mortgage brokers, solicitors, tax advisers and property managers can simplify the process for overseas investors.
    Buy-to-Let can be suitable for remote investors. Professional letting agents can handle tenant finding, rent collection and day-to-day management.
    Currency fluctuations affect returns. Exchange rate movements can affect the effective cost of a property and the value of rental income when converted into another currency.
    Deal sourcers help investors find opportunities. Local deal sourcers can provide access to investment opportunities and market knowledge without requiring the investor to be physically present.
    Building the right team is essential. A reliable network of UK-based professionals can help overseas investors manage the investment remotely.
    Technology makes investing easier. Many parts of the property investment process can now be handled remotely, although some tasks still require local support.
    Sylvest connects investors with UK deal sourcers. Investors can browse opportunities, define their requirements and connect with deal sourcers through the platform.

    Why Overseas Investors Choose UK Property

    Investing in UK property from abroad can appeal to investors who want exposure to an established property market without relocating to the UK.

    There are several strategies available, including Buy-to-Let, HMO, Serviced Accommodation and other specialist property investments. This gives overseas investors flexibility when building a portfolio around their budget and objectives.

    However, the attractiveness of the market should not be confused with simplicity. Overseas investors need to consider financing, tax, currency movements, property management and local due diligence before committing to a purchase.

    Therefore, choosing the right investment structure and professional support can be just as important as choosing the property itself.

    Can Overseas Investors Buy UK Property?

    Yes. Overseas investors can purchase UK property, although the process can vary depending on their residency, financial circumstances, the property type and where in the UK the property is located.

    If you are not buying with cash, financing requires particular attention. Some UK lenders do not lend to non-UK residents, while specialist lenders and private banks may offer products for international buyers.

    For that reason, a UK mortgage broker with experience in international buyers can be an important first point of contact.

    Tax is another area that needs careful consideration. UK rental income can be taxable even when the property owner lives overseas. HMRC’s Non-resident Landlords Scheme applies to landlords whose usual place of abode is outside the UK, with rules covering how rental income is paid and when tax may be deducted.

    There can also be additional purchase taxes. For example, non-UK residents buying residential property in England and Northern Ireland can be subject to a 2% SDLT surcharge, subject to the applicable rules and exemptions.

    Which Strategies Work Best for Investing in UK Property from Abroad?

    Not every property strategy is equally suited to remote management. Some require more hands-on involvement, while others can be structured around professional local management.

    Buy-to-Let can work well remotely when a professional letting agent manages the property. The agent can handle tenant finding, rent collection, maintenance coordination and other day-to-day tasks, leaving the investor with a more strategic role.

    HMO can also work for overseas investors, particularly when an experienced HMO specialist manages the property. However, multiple tenants can create greater management and maintenance requirements, making the quality of the local management team particularly important.

    Serviced Accommodation is generally more operationally intensive. Guest communication, bookings, cleaning, maintenance and frequent turnover can be difficult to manage from another country without a local co-host or specialist management company.

    Finally, deal sourcing can help solve the initial access problem. A local deal sourcer can identify potential opportunities, provide relevant deal information and help an overseas investor assess whether a property is worth investigating further.

    What You Need Before Investing in UK Property from Abroad

    Beyond the right mortgage product, overseas investors typically need several key pieces of support.

    • A UK solicitor: A solicitor can handle conveyancing and other legal aspects of the purchase. Many firms regularly work with overseas clients, but it is sensible to confirm this before instructing one.
    • Currency transfer planning: The exchange rate between your home currency and sterling can affect the effective cost of the property. Larger transactions may also make currency management particularly important.
    • A suitable banking arrangement: A UK bank account is not necessarily required in every situation, but having an appropriate way to receive rental income and pay UK property costs can make ongoing management easier.
    • Tax advice: Overseas investors should understand their UK tax position before purchasing. UK rental income can remain taxable even when the owner lives abroad, while their country of residence may have its own tax rules. HMRC provides specific guidance for non-resident landlords.
    • Local property management: If you are not going to visit the property regularly, you need to know who will handle inspections, repairs, tenants and other practical matters.

    Understanding Currency and Transfer Costs

    Currency fluctuation is a genuine consideration for overseas investors. A property that looks attractive in pounds sterling can have a very different effective cost when converted into your home currency.

    The same applies to rental income. If you receive £1,500 per month in rent, the amount you ultimately receive in your home currency can change as exchange rates move.

    For larger transactions, investors may consider specialist currency services or hedging products. However, the suitability of these options depends on your circumstances, so professional advice may be appropriate before committing to a purchase.

    The important point is to assess the investment in both GBP terms and your home currency. This gives you a clearer picture of the actual capital required and the potential income you will receive.

    How Deal Sourcers Reduce the Complexity

    The biggest practical challenge for many overseas investors is finding the right property without being physically present in the UK.

    This is where deal sourcers can add value. A good UK deal sourcer may have local market knowledge and relationships with estate agents, developers and private vendors. They can identify potential opportunities and present relevant information before the investor decides whether to investigate further.

    On Sylvest, deal sourcers can list investment opportunities with supporting deal information. Investors can review details such as comparable rents, yield projections, EPC ratings and the deal sourcer’s notes before deciding whether to proceed.

    However, deal sourcing does not remove the need for independent due diligence. Investors should verify important financial, legal and property information before committing funds.

    How Sylvest Supports Overseas Investors

    Sylvest is designed to make it easier for investors to connect with UK deal sourcers regardless of where they are based.

    Investors can browse opportunities and connect directly with deal sourcers. They can also post a Deals Wanted listing covering their preferred location, budget, strategy and deal type. Sourcers with potentially suitable opportunities can then respond.

    This two-way approach can reduce one of the biggest challenges faced by overseas investors: finding relevant local opportunities without already having an established UK property network.

    Technology can also make the process easier. Documents can be reviewed remotely, conversations can take place online and many aspects of the investment process can be coordinated without the investor travelling to the UK.

    However, remote investing still requires local support when physical inspections, surveys, repairs, property management or other on-the-ground tasks are necessary.

    “The barriers to investing in UK property from overseas are smaller than most people think. The bigger barrier is knowing where to start.”

    The Bottom Line

    Investing in UK property from abroad is possible, but successful remote investing requires more planning than simply finding a property and making an offer.

    The right strategy, mortgage broker, solicitor, tax adviser, letting agent and other professionals can make the process significantly easier. At the same time, overseas investors need to account for currency movements, management arrangements, transaction costs and UK tax requirements.

    Deal sourcers can help bridge the local knowledge gap by finding and presenting opportunities that overseas investors may not discover themselves. Sylvest provides a platform where investors can connect with deal sourcers and search for opportunities based on their investment requirements.

    The objective should not be to invest remotely simply for convenience. Instead, it is to build a UK property investment process that can work effectively even when you are not physically in the country.

  • Understanding Why Off-Market Property Deals Are Attractive

    Understanding Why Off-Market Property Deals Are Attractive

    Not all property transactions take place on the open market. Off-market property deals are opportunities that are not publicly advertised through the usual property portals or widely marketed by estate agents. Instead, they can be introduced through private networks, deal sourcers, direct vendor relationships and specialist property platforms.

    For investors, the attraction is straightforward. There may be less competition, earlier access to opportunities and more scope for direct conversations with sellers. However, off-market does not automatically mean below market value or better returns. The investment still needs to make sense after proper research and due diligence.

    This guide explains why off-market property deals attract investors, how they work in the UK and what investors should consider before pursuing one.

    Quick Summary

    Takeaway Explanation
    Off-market property deals offer private access. These opportunities are not generally advertised across the main property portals and may instead be introduced through private networks, deal sourcers or direct vendor relationships.
    Competition can be lower. Fewer buyers may know about an opportunity, potentially giving investors more room to negotiate.
    Several types of off-market deal exist. Opportunities can include BMV properties, distressed sales, pre-market opportunities, packaged deals and direct vendor transactions.
    Networking is important. Strong relationships with deal sourcers, estate agents, developers and vendors can provide access to opportunities before wider marketing.
    Negotiation may be more flexible. Private discussions can sometimes give buyers and sellers greater scope to negotiate price and terms.
    Deal sourcers can save investors time. Sourcers identify potential opportunities and can provide supporting information before the investor decides whether to proceed.
    Due diligence remains essential. An off-market property still requires appropriate financial, legal, planning and physical checks before an investment decision is made.
    Specialist platforms can broaden access. Platforms such as Sylvest can connect investors with deal sourcers and opportunities beyond traditional public listings.

    Defining Off-Market Property Deals: What They Are

    Off-market property deals are transactions where a property is offered to selected buyers without being widely advertised to the public.

    Instead of appearing prominently on property portals, an opportunity might be introduced through a deal sourcer, estate agent, developer, private investor or direct relationship with the property owner.

    A seller may choose this approach for several reasons. They might value privacy, want to test demand before launching a full marketing campaign, prefer a faster transaction or simply have an existing relationship with a potential buyer.

    Therefore, off-market does not mean that a property is hidden or unavailable. It means the opportunity is being circulated through a more limited network.

    “Off-market doesn’t mean hidden from everyone. It means hidden from the crowd, which is exactly where serious investors want to be.”

    The Core Characteristics of Off-Market Property Deals

    Off-market transactions are generally characterised by limited public exposure and more targeted communication.

    Important characteristics include:

    • No widespread public listing
    • Direct or limited communication between buyers and sellers
    • Potentially lower buyer competition
    • Greater privacy around the transaction
    • Opportunities introduced through professional networks
    • Deal matching based on specific investor requirements

    However, investors should not assume that limited exposure automatically creates a bargain. The property’s price still needs to be assessed against comparable sales, rental demand, condition and the intended investment strategy.

    For properties in England and Wales, investors can also use HM Land Registry information to investigate ownership, tenure, previous sale prices and other registered details.

    How Off-Market Property Deals Operate

    Off-market property deals can originate from several different channels. Deal sourcers may hear about a property through their professional network, while estate agents and developers may approach investors directly about suitable opportunities.

    Common sources include:

    • Property investment networking communities
    • Relationships with estate agents
    • Direct approaches to property owners
    • Developer and professional contacts
    • Deal sourcers with established local networks
    • Specialist property investment platforms

    The key difference is that investors are not relying solely on a public search for available properties. Instead, they are building or accessing networks that can bring opportunities to them.

    Why Off-Market Property Deals Are Attractive

    The appeal of off-market property deals goes beyond simply finding a property that is not listed online.

    For investors, the real attraction can be earlier access, reduced competition and the opportunity to have a more direct conversation with the seller or intermediary.

    Strategic Investment Advantages

    One of the biggest potential advantages is reduced competition.

    A property listed publicly can attract interest from a large pool of buyers. Multiple offers can then create competitive pressure, particularly when the property is well priced.

    An off-market opportunity may initially be shown to a smaller group of investors. Consequently, a buyer may have more time to assess the opportunity and potentially negotiate without competing against a large number of buyers.

    Other potential advantages include:

    • Less competition
    • Earlier access to investment opportunities
    • Potentially greater negotiation flexibility
    • Access to motivated sellers
    • Greater transaction privacy

    However, these are potential advantages rather than guarantees. A strong off-market opportunity can still attract several buyers, particularly when a deal sourcer presents it to an established investor network.

    Networking and Information Leverage

    Professional relationships are particularly important when accessing off-market property deals.

    Deal sourcers, investors, estate agents, developers and property owners can all act as sources of information. The stronger these relationships become, the more likely an investor is to hear about relevant opportunities.

    Investors can build these relationships through:

    • Property networking events
    • Direct conversations with property owners
    • Relationships with estate agents
    • Deal sourcer networks
    • Specialist property investment platforms

    The objective is not simply to collect contacts. Instead, it is to build credible relationships so that people understand exactly what type of property you are looking for.

    How Off-Market Property Deals Work in Property Investment

    Off-market transactions rely heavily on communication, trust and professional relationships.

    Unlike a standard public listing, where much of the initial information is available to anyone, an off-market opportunity is often introduced directly to a specific investor or a smaller group.

    The Mechanics of Private Property Transactions

    The process can vary depending on the deal, but it may follow a structure such as:

    1. A seller or intermediary identifies a potential opportunity.
    2. The opportunity is introduced to a suitable investor or deal sourcer network.
    3. The investor reviews the initial property and financial information.
    4. Further questions and negotiations take place.
    5. The investor carries out appropriate due diligence.
    6. If the numbers and property fundamentals work, the parties proceed towards an offer and transaction.

    This can make the process more targeted than searching through hundreds of publicly advertised properties.

    However, the lack of a public listing should never be treated as a reason to reduce due diligence. UK property transactions still require appropriate legal and financial checks. Government guidance notes that buyers typically use professionals such as conveyancers and surveyors and undertake checks on the property before completing.

    Networking and Information Exchange

    An investor’s ability to build and maintain professional relationships can have a significant influence on access to off-market property deals.

    Strong communication between investors, estate agents, deal sourcers, developers and property owners can create useful information channels.

    The process involves:

    • Building trust within investment communities
    • Developing a reputation for reliable transactions
    • Maintaining consistent professional communication
    • Understanding specific local markets
    • Clearly communicating your investment criteria
    • Demonstrating that you can act when a suitable opportunity appears

    For an investor, being clear about location, budget, strategy and target returns can make it easier for others to identify suitable opportunities.

    Key Advantages of Pursuing Off-Market Property Deals

    For investors operating in a competitive property market, off-market property deals can provide another route to finding suitable investments.

    The potential advantages extend beyond price. Access, timing, privacy and negotiation can all play a role.

    Competitive Edge and Strategic Positioning

    The main advantage is potentially avoiding the level of competition associated with a widely advertised property.

    This can provide investors with:

    • Less competition from other buyers
    • Earlier access to selected opportunities
    • Greater flexibility during negotiations
    • Potentially more direct communication with sellers
    • Faster identification of suitable properties

    Nevertheless, investors should remain realistic. An off-market property is not automatically a discounted property.

    Propertymark guidance, for example, stresses the importance of accurate and fair property information and warns against unsupported claims about market value.

    Financial and Operational Benefits

    The financial benefit of off-market property deals comes from the possibility of identifying a suitable property at a price and on terms that work for the investor.

    Potential benefits include:

    • Reduced exposure to bidding competition
    • Access to motivated sellers
    • Potential for value creation
    • More targeted property searches
    • Less time spent reviewing unsuitable public listings

    However, investors should compare the opportunity against the wider market. They should consider comparable sales, rental demand, refurbishment requirements, financing, taxes and transaction costs before deciding whether the deal represents genuine value.

    This table summarises some of the main differences:

    Aspect On-Market Deals Off-Market Deals
    Visibility Publicly advertised on property portals and agent websites Shared through private networks or targeted channels
    Competition Potentially high May be lower, depending on the opportunity
    Negotiation Can be influenced by competing offers May allow more direct negotiation
    Access Available to the wider market Usually limited to selected buyers
    Privacy Information is more widely available Greater privacy may be possible
    Deal Matching Investor searches available listings Opportunities can be matched to specific criteria

    How Sylvest Helps Investors Access Off-Market Property Deals

    Finding off-market property deals has traditionally depended heavily on personal networks and relationships.

    Sylvest provides another way for investors to access these opportunities.

    On Sylvest, deal sourcers can list investment opportunities and connect directly with investors. Investors can search according to their preferred strategy, location and investment requirements rather than relying exclusively on public property portals.

    Investors can also use the Deals Wanted approach to explain what they are looking for. This can include location, budget, strategy and preferred deal type. Deal sourcers with potentially suitable opportunities can then respond.

    That creates a two-way model. Investors can search for deals, while deal sourcers can search for investors whose requirements match their opportunities.

    For investors who are reviewing an off-market opportunity, proper due diligence remains essential. HM Land Registry provides property information for England and Wales, including title details, ownership and other registered information.

    Frequently Asked Questions

    What are off-market property deals?

    Off-market property deals are property opportunities that are not widely advertised through the conventional public market. They may be introduced through deal sourcers, estate agents, developers, private networks or direct vendor relationships.

    What are the main benefits of off-market property deals?

    The potential benefits include lower competition, earlier access to opportunities, greater privacy and more direct negotiation. However, an off-market property is not automatically cheaper or more profitable.

    How do off-market property deals work?

    They generally rely on private communication and professional networks. A deal sourcer, agent, developer or property owner introduces an opportunity to a selected investor or group of investors, after which the buyer reviews the information and carries out due diligence.

    How can investors find off-market property deals?

    Investors can build relationships with estate agents, developers and property owners, attend property networking events, work with deal sourcers and use specialist property investment platforms such as Sylvest.

    The Bottom Line

    Off-market property deals can give investors access to opportunities that may never appear on the major property portals. Less competition, earlier access and potentially greater negotiation flexibility make them attractive to investors who know what they are looking for.

    However, the word “off-market” should never be mistaken for “better value”. The fundamentals still matter. Investors should assess the property’s price, location, rental demand, condition, financing, legal position and potential returns before proceeding.

    The real advantage comes from combining access with good investment judgement.

    Sylvest brings investors and deal sourcers together in one platform, creating a more structured way to discover property opportunities and build professional relationships.

    The goal is not simply to find a property that is off-market. It is to find an off-market property deal that actually makes sense.

  • What is Commercial Property Investment? Understanding the Basics

    What is Commercial Property Investment? Understanding the Basics

    Commercial property investment involves buying, owning or investing in property used for business and other non-residential purposes. Offices, retail units, industrial warehouses, hospitality properties and specialist commercial buildings can all form part of this market.

    For investors, the attraction is usually a combination of rental income, potential capital growth and portfolio diversification. However, commercial property is not simply residential property on a larger scale. Lease structures, tenant requirements, financing, valuation, operating costs and market risks can all be different.

    This guide explains commercial property investment, the main types of commercial property, how investors make money, and the risks that should be considered before committing capital.

    What Is Commercial Property Investment?

    Commercial property investment is the purchase or ownership of property intended primarily for business or other non-residential use, with the objective of generating income, capital growth or both.

    Unlike a typical residential Buy-to-Let, the occupier is usually a business or organisation rather than an individual household. This can create different investment dynamics, particularly around leases, rent reviews, property requirements and tenant obligations.

    Commercial property can also vary considerably in scale. An investor might purchase a small retail unit, an office building, an industrial warehouse or a larger mixed-use asset.

    The investment case therefore depends heavily on the specific property, tenant, lease and location rather than simply the fact that the asset is commercial.

    The Main Types of Commercial Property

    There are several major categories within commercial property investment, and each has its own demand drivers and risks.

    Office Properties

    Office property ranges from small professional suites to larger city-centre buildings and suburban office parks.

    Demand can depend on factors such as location, transport connections, local employment, building quality and changing working patterns. Investors should also consider the lease structure and the financial strength of the occupier.

    Retail and High Street Properties

    Retail property includes individual shops, shopping centres, retail parks and other premises used by businesses selling goods or services.

    Footfall, accessibility, local demographics and the strength of surrounding businesses can all influence demand. However, retail property can also be particularly sensitive to changes in consumer behaviour and the wider retail market.

    Industrial and Logistics Property

    Industrial units and warehouses are used for manufacturing, storage, distribution and logistics.

    Location can be particularly important for these assets. Access to major roads, transport networks, labour markets and distribution hubs can influence tenant demand.

    Hospitality and Specialist Commercial Property

    Hotels, serviced accommodation, medical facilities and other specialist properties can also fall within the wider commercial property market.

    These assets often have more specific operational requirements. Consequently, investors need to understand not only the property itself but also the business activity taking place within it.

    Why Commercial Property Investment Can Be Attractive

    The potential appeal of commercial property investment comes from several different sources.

    First, commercial property can generate rental income from business occupiers. Depending on the lease, the investor may also benefit from contractual rent reviews or other mechanisms that can increase income over time.

    Second, there is the potential for capital growth. If the property’s market value increases, an investor may benefit when the asset is eventually refinanced or sold.

    Finally, commercial property can provide another asset class within a wider property portfolio. An investor who already owns residential property may use commercial assets to diversify the types of property and tenants they are exposed to.

    However, none of these outcomes is guaranteed. Property values and rental income can be affected by economic conditions, tenant demand, interest rates and local market changes.

    How Commercial Property Investment Works

    The basic process is similar to other forms of property investment, but the analysis can be more detailed.

    An investor first identifies a suitable commercial property and assesses whether its price reflects the expected income and risks. The investor then considers financing, the existing or potential tenant, the lease, operating costs and the wider market.

    Investment Acquisition and Valuation

    Valuation is particularly important in commercial property investment because the income produced by the property can have a significant influence on its value.

    Investors may assess:

    • Current rental income
    • Market rent
    • Lease length and remaining term
    • Rent review provisions
    • Tenant financial strength
    • Comparable transactions
    • Location and local demand
    • Property condition
    • Potential for refurbishment or change of use

    Professional valuation can involve different approaches depending on the property and purpose. RICS guidance covers commercial property valuation and the methods used by professional valuers.

    Revenue Generation in Commercial Property

    There are two primary ways an investor can potentially make money from a commercial property:

    Rental income: The property generates income from its occupier under the terms of the lease.

    Capital growth: The property may increase in value over time, allowing the investor to benefit from a higher sale price or valuation.

    Some investments can also create additional value through refurbishment, improved management, lease restructuring or changes to the property’s use, although these strategies carry their own costs and risks.

    How Commercial Property Costs Affect Returns

    Headline rental income does not tell you the full story.

    Investors need to consider the costs associated with owning and operating a commercial property. Depending on the property and lease, these can include:

    • Maintenance and repairs
    • Insurance
    • Professional and management fees
    • Financing costs
    • Void periods
    • Refurbishment
    • Legal and valuation costs
    • Business rates and other property-related costs

    Business rates are particularly relevant to many non-domestic properties. In England, business rates are calculated using the property’s rateable value and an applicable multiplier, while the rules differ in Scotland and Northern Ireland.

    The actual responsibility for costs between landlord and tenant will depend on the lease. Therefore, investors should examine the lease carefully rather than assuming that every commercial property operates in the same way.

    The Benefits and Risks of Commercial Property Investment

    Like any investment strategy, commercial property investment involves both potential rewards and risks.

    Potential Benefits of Commercial Property Investment

    Commercial property can offer several potential advantages:

    • Rental income: Business tenants can provide an ongoing income stream.
    • Potential capital growth: Property values may increase over time.
    • Portfolio diversification: Commercial assets can complement residential property investments.
    • Potential for value creation: Refurbishment, re-letting or improving the property’s income profile may create additional value.
    • Different lease structures: Commercial leases can provide longer-term arrangements depending on the property and tenant.

    Critical Risk Factors

    The risks also need careful consideration.

    Tenant risk is important. If a business tenant fails or leaves the property, the investor may face a period without rental income and additional costs to find a replacement.

    Market risk can also affect both rents and property values. Economic downturns can reduce demand for particular types of commercial property.

    Financing risk is another consideration. Changes in interest rates can increase borrowing costs and affect the viability of highly leveraged investments.

    Finally, commercial properties can sometimes be more specialised than residential properties. A property designed for a particular occupier may take longer to re-let if demand changes.

    Strategic Risk Management

    Investors can reduce some of these risks through careful planning and due diligence.

    Before committing to a commercial property investment, consider:

    • The financial strength of the tenant
    • Remaining lease term
    • Rent review provisions
    • Current and achievable market rent
    • Property condition
    • Local demand
    • Comparable property values
    • Financing costs
    • Potential void periods
    • Required capital expenditure

    Keeping appropriate cash reserves is also important, particularly where the property may require significant maintenance or refurbishment.

    How to Evaluate a Commercial Property Investment

    A strong commercial property deal should make sense beyond its headline yield.

    Start by understanding the income. How much rent is being paid, when is the next rent review and how secure is the existing tenancy?

    Next, examine the property. Consider its condition, location, specification and suitability for the current and potential future occupiers.

    Then assess the tenant and lease. A high rent is less attractive if the tenant is financially weak or the lease provides limited security.

    Finally, model the costs and downside scenarios. What happens if the property becomes vacant? What if interest rates increase? How much capital expenditure could be required?

    For properties in England and Wales, investors can also review official business-rate information and rateable values through GOV.UK when relevant to the property. The 2026 revaluation introduced new rateable values from 1 April 2026, so current figures should be checked rather than relying on historic assumptions.

    How Sylvest Helps Investors Find Commercial Property Opportunities

    Finding the right commercial property investment can be challenging, particularly for investors who do not have an established network of agents, developers and deal sourcers.

    Sylvest provides a platform where investors can connect with deal sourcers and explore property opportunities based on their preferred strategy and requirements.

    Investors can review available opportunities and communicate directly with the deal sourcer behind the deal. They can also use the Deals Wanted approach to specify their preferred location, budget, property type and investment strategy.

    This creates a two-way process. Investors can search for commercial opportunities while deal sourcers can identify investors whose requirements match their available properties.

    However, a deal listing should be treated as the starting point for investigation rather than the final investment decision. Investors should independently verify financial information, lease details, valuation, property condition and other relevant factors before proceeding.

    The Bottom Line

    Commercial property investment can provide investors with exposure to rental income, potential capital growth and a different part of the property market.

    However, commercial property is not automatically a better investment than residential property. The quality of the tenant, lease, location, property and purchase price all matter. Operating costs and financing can also have a significant effect on the final return.

    The strongest commercial property investments are not necessarily the ones with the highest headline yield. They are the opportunities where the income, property fundamentals, tenant quality, lease structure and purchase price work together.

    For investors looking to explore commercial opportunities, Sylvest provides a route to connect with deal sourcers and discover investment properties based on specific requirements.

    The objective is simple: understand the asset, understand the numbers and understand the risks before you invest.

    Frequently Asked Questions

    What is commercial property investment?

    Commercial property investment involves purchasing or owning property used for business or other non-residential purposes, with the aim of generating rental income, capital growth or both.

    What are the main types of commercial property?

    The main categories include office buildings, retail units, industrial and logistics properties, hospitality assets and specialist properties such as medical facilities.

    How does commercial property investment generate income?

    Commercial properties can generate rental income from business tenants. Investors may also benefit from capital growth if the property’s value increases over time.

    What are the main risks of commercial property investment?

    Key risks include tenant failure or vacancy, changes in market demand, interest-rate movements, maintenance costs, financing risk and changes in property values.

    Is commercial property investment better than residential property investment?

    There is no universal answer. Commercial and residential property have different income characteristics, costs, risks and management requirements. The right choice depends on the investor’s objectives, capital, risk tolerance and investment strategy.

  • Property Investment Platforms Explained: What They Are and How They Work

    Property Investment Platforms Explained: What They Are and How They Work

    Property investment has traditionally relied on personal networks, property agents, deal sourcers, local knowledge and significant amounts of research. However, property investment platforms have changed how investors discover opportunities, review information and connect with people involved in property transactions.

    Instead of relying entirely on traditional channels, investors can now use digital platforms to access property opportunities, market information, investment analysis and direct connections with deal sourcers. The exact experience depends on the type of platform, as some focus on connecting investors with property opportunities, while others facilitate crowdfunding, fractional ownership or other investment structures.

    Understanding how these platforms work is important because a platform is only the starting point. Investors still need to understand the underlying property, financial structure, risks, costs and any regulatory considerations before committing capital.

    What Is a Property Investment Platform?

    A property investment platform is a digital service that brings together property investment opportunities, investors, deal sourcers and supporting information in one place.

    The purpose is to make parts of the investment process more organised and accessible. Instead of searching across numerous sources, investors may be able to browse opportunities, review property information, compare deals and communicate with the people presenting them through a centralised system.

    However, not every property investment platform operates in exactly the same way.

    Some platforms act primarily as a marketplace connecting property investors with deal sourcers. Others allow investors to participate in property development funding, fractional ownership or other investment structures.

    This distinction matters because the level of regulation, investor protection and involvement in the underlying property can vary considerably between platforms.

    The original article highlights several common platform functions, including centralised property opportunities, market information, transaction support, risk assessment and communication between investors and deal sourcers.

    How Property Investment Platforms Work

    Although individual platforms differ, the basic process is relatively straightforward.

    1. Property Opportunities Are Added

    The first stage is usually the introduction of property opportunities to the platform.

    Depending on the platform’s business model, these opportunities may come from:

    • Deal sourcers
    • Property developers
    • Estate and property professionals
    • Investment companies
    • Property owners
    • Development businesses

    A deal sourcer may identify an opportunity, assess the property and prepare the relevant information before presenting it to potential investors.

    2. Investors Review Available Opportunities

    Investors can then browse opportunities that match their investment objectives.

    Information may include:

    • Property type and location
    • Purchase price
    • Expected rental income
    • Estimated refurbishment costs
    • Potential exit strategy
    • Expected returns
    • Development information
    • Comparable property information
    • Key risks and assumptions

    The amount and quality of information will vary between platforms, so investors should not assume that every opportunity has been independently verified.

    3. Investors Carry Out Their Own Due Diligence

    This is one of the most important stages.

    A property investment platform can make opportunities easier to discover, but it does not remove the investor’s responsibility to investigate the opportunity.

    Depending on the transaction, due diligence may include:

    • Reviewing legal documents
    • Checking ownership and title information
    • Assessing rental demand
    • Reviewing comparable sales and rents
    • Understanding refurbishment requirements
    • Checking planning considerations
    • Assessing financing assumptions
    • Reviewing the proposed exit strategy
    • Understanding taxes and transaction costs

    The platform should therefore be viewed as a tool for accessing and assessing opportunities, rather than a replacement for professional advice or investor due diligence.

    Different Types of Property Investment Platforms

    The term property investment platform covers several different business models.

    Property Deal Marketplaces

    These platforms connect property investors with property opportunities, often through deal sourcers.

    The investor may ultimately purchase the property directly rather than investing money into the platform itself.

    This model can be particularly useful for investors who want access to opportunities they may not otherwise find through the traditional property market.

    Property Crowdfunding Platforms

    Crowdfunding platforms allow multiple investors to contribute capital towards a property-related project or investment.

    The investment could involve lending money to a property business or investing in a business or security connected with a property project.

    The FCA notes that crowdfunding can involve different structures, and some forms are regulated while others are not. Property development crowdfunding also carries specific risks, including the possibility of losing invested capital if a project fails.

    Fractional or Shared Property Investment

    Some platforms allow investors to participate in a property without purchasing the entire asset themselves.

    This can lower the amount of capital required, but investors need to understand exactly what they own, how income is distributed, what fees apply and how they can exit the investment.

    The legal and financial structure is therefore just as important as the property itself.

    What Features Should You Look For in a Property Investment Platform?

    Not all platforms offer the same functionality. A useful platform should make it easier to understand opportunities rather than simply presenting a large number of listings.

    Clear Property Information

    Investors should be able to understand the fundamentals of an opportunity without having to search through multiple sources.

    Useful information can include property details, location, asking price, expected income, costs, investment strategy and supporting documentation.

    Deal Sourcer Information

    Where opportunities are provided by deal sourcers, investors should be able to understand who sourced the opportunity and what role they have in the transaction.

    Transparency around the deal sourcer can help investors assess the quality and credibility of the information being presented.

    Financial Analysis

    Good platforms can make financial information easier to interpret through structured calculations and investment metrics.

    Depending on the investment strategy, these may include:

    • Gross and net rental yields
    • Cash flow
    • Purchase costs
    • Refurbishment costs
    • Financing assumptions
    • Capital growth assumptions
    • Projected returns
    • Exit values

    However, projected returns should always be treated as estimates rather than guaranteed outcomes.

    Communication Tools

    Direct communication between investors and deal sourcers can also improve the investment process.

    Questions about the property, assumptions, documents or investment strategy can be addressed before an investor decides whether to proceed.

    What Are the Benefits of Property Investment Platforms?

    A well-designed property investment platform can make the property investment process more efficient, particularly for investors who struggle to find suitable opportunities through traditional channels.

    Greater Access to Opportunities

    Investors can potentially discover opportunities beyond their immediate geographical area or existing professional network.

    For example, an investor based in Manchester may be able to discover a deal in Birmingham, Liverpool or another UK market without having an established local network there.

    More Efficient Deal Discovery

    Searching for property opportunities manually can take considerable time.

    A platform can bring opportunities together in one environment, allowing investors to filter and compare deals more efficiently.

    Better Organisation of Information

    Instead of receiving property information through separate emails, messages and documents, a platform can organise important information around individual opportunities.

    This can make the initial screening process easier.

    Easier Investor and Deal Sourcer Connections

    For investors who do not have an extensive property network, platforms can provide a structured way to connect with deal sourcers who are actively sourcing opportunities.

    This is particularly relevant in the off-market property sector, where suitable opportunities may not always appear on the mainstream property portals.

    Are Property Investment Platforms Regulated?

    This is an important question because property investment platforms are not all regulated in the same way.

    The FCA regulates certain investment platforms and crowdfunding activities. For example, investment platforms are included among consumer investment firms that require FCA authorisation where they carry out regulated activities.

    At the same time, the FCA makes clear that some investment products and activities are outside its regulatory perimeter. Therefore, investors should not assume that a platform is regulated simply because it operates online or describes itself as an investment platform.

    Before investing, check:

    • Whether the platform is FCA authorised where relevant
    • What activity the authorisation covers
    • Who actually holds your money
    • What fees apply
    • What happens if the platform fails
    • Whether your investment is covered by any investor protection scheme
    • Whether you are investing directly in property, lending money or buying another type of investment

    The FCA’s Financial Services Register can be used to check the regulatory status of firms carrying out regulated activities.

    What Are the Risks of Using a Property Investment Platform?

    Digital platforms can improve access and efficiency, but they do not eliminate property investment risk.

    Property values can fall, rental income can be lower than expected, refurbishment costs can increase and development projects can experience delays.

    There can also be platform-specific risks.

    For example, if an investor participates in a property development through a crowdfunding structure, the investment could be exposed to the financial position of the developer as well as the underlying property.

    The FCA specifically warns that property development crowdfunding can involve a higher risk of losing invested money if the development company cannot complete the project or repay the investment.

    Therefore, investors should assess both the property opportunity and the platform through which it is being offered.

    How Sylvest Uses the Property Investment Platform Model

    Sylvest is designed around a different part of the property investment process.

    Rather than attempting to replace every stage of property ownership or investment, the platform focuses on bringing deal sourcers and property investors together.

    For investors, this means having a central place to discover property opportunities and assess whether they fit their investment strategy.

    For deal sourcers, it provides a structured environment through which suitable property opportunities can be presented to potential investors.

    The objective is to make the connection between the two sides more straightforward, while giving investors better visibility of the opportunities they are considering.

    The platform itself does not remove the need for investor due diligence. Instead, it is intended to make the process of discovering and evaluating potential property deals more organised.

    The Bottom Line

    A property investment platform can make it easier for investors to discover opportunities, access information and connect with deal sourcers or other property professionals.

    However, platforms are not all the same. Some operate as property deal marketplaces, while others facilitate crowdfunding, fractional ownership or other investment structures.

    The most important question is therefore not simply whether a platform offers attractive property opportunities. Investors should understand how the platform works, what they are actually investing in, who is responsible for the information provided, what fees apply and what risks they are taking.

    Used properly, a property investment platform can become a valuable part of an investor’s property research and deal-sourcing process. It should complement, rather than replace, proper due diligence and professional advice where required.

    Frequently Asked Questions

    What is a property investment platform?

    A property investment platform is an online service that helps investors discover property opportunities, access investment information and connect with deal sourcers, developers or other property professionals.

    How does a property investment platform work?

    Typically, property opportunities are presented through the platform, investors review the available information, carry out their own due diligence and decide whether an opportunity fits their investment strategy.

    Are property investment platforms regulated in the UK?

    Some activities carried out by investment platforms and crowdfunding platforms are regulated by the FCA, but not every property-related platform or investment product is regulated in the same way. Investors should check the specific firm’s status and permissions before investing.

    Can I invest in property with less money through a platform?

    Some platforms offer structures such as crowdfunding or fractional investment that can reduce the amount of capital required to participate. However, the minimum investment, ownership structure, fees and risks vary between platforms.

    Are property investment platform returns guaranteed?

    No. Property investment returns are not guaranteed. Rental income, property values, development costs and exit values can all differ from initial projections.

  • Understanding Investment Opportunities in UK 2025

    Understanding Investment Opportunities in UK 2025

    The UK property market continues to offer a wide range of Investment Opportunities for people looking to build long-term wealth, generate rental income or diversify their portfolios. However, finding the right opportunity involves more than simply choosing a property that appears affordable or promising.

    In 2025, technology, economic conditions, planning changes and sustainability have all influenced the way investors approach the property market. Investment Opportunities can be found across residential property, commercial property, development projects and specialised sectors. The key is understanding the market, assessing the risks and choosing an investment that matches your financial goals.

    What Are Investment Opportunities and Why Do They Matter?

    An investment opportunity is an asset, project or business where an investor commits capital with the expectation of receiving a financial return in the future.

    These opportunities can exist across different areas, including:

    • Property
    • Shares
    • Bonds
    • Businesses
    • Technology companies
    • Development projects
    • Alternative investments

    For property investors, an opportunity could involve purchasing a buy-to-let property, investing in an HMO, acquiring a commercial building or purchasing a property with potential for renovation and value improvement.

    However, an attractive investment is not simply one with a high expected return. Investors should also consider the level of risk, amount of capital required, expected timeframe and potential exit strategy.

    What Makes an Investment Opportunity Attractive?

    Several factors can make an investment worth investigating further:

    • Potential for reliable income
    • Potential for long-term capital growth
    • Strong local demand
    • A realistic purchase price
    • Manageable investment risk
    • A clear investment strategy
    • Alignment with the investor’s financial goals

    For example, a property with a high projected rental yield may not necessarily be a good investment if it requires significant renovation or has weak tenant demand.

    Therefore, investors should look at the complete investment rather than focusing on one financial figure.

    Key Trends Shaping UK Investment Opportunities in 2025

    The UK property market in 2025 has been influenced by economic conditions, technology, planning policy and changing investor preferences.

    Understanding these trends can help investors identify potential Investment Opportunities while also recognising the risks associated with changing market conditions.

    Technology and Property Investment

    Technology is changing how property investors search for and assess opportunities.

    Property technology, commonly known as PropTech, has introduced tools that can make property research and investment analysis more efficient.

    For instance, technology can help investors with:

    • Property searches
    • Market research
    • Property valuation
    • Financial analysis
    • Portfolio management
    • Virtual property viewings
    • Data comparison

    More importantly, better access to information can help investors compare different properties and identify opportunities that fit their investment criteria.

    Even so, technology should support investment decisions rather than replace proper research and due diligence.

    Planning and Development

    Planning policy is another important consideration for property investors.

    Changes to planning rules can affect development, property conversions and changes of use. As a result, investors considering development or value-add projects should understand the relevant planning requirements before committing capital.

    A property may appear to have significant development potential, but that potential depends on planning permission, local policies, costs and the feasibility of the proposed project.

    Sustainability and Energy Efficiency

    Sustainability is also becoming more important in property investment.

    Investors may consider:

    • Energy Performance Certificate ratings
    • Energy efficiency improvements
    • Building condition
    • Heating systems
    • Renewable energy options
    • Future regulatory requirements

    In addition, energy efficiency can affect the costs of operating and improving a property.

    For investors, sustainability should therefore be considered alongside the property’s financial performance and long-term potential.

    Understanding Different Types of UK Property Investment

    There are several types of property Investment Opportunities available in the UK. Each strategy has different characteristics, costs and risks.

    Residential Property Investment

    Residential property remains one of the most common forms of property investment.

    Potential opportunities include:

    • Houses
    • Flats and apartments
    • Buy-to-let properties
    • HMOs
    • Student accommodation
    • Refurbishment projects

    The potential performance of a residential investment depends on factors such as location, rental demand, purchase price, financing costs, operating expenses and future property values.

    For example, a property in an area with strong employment, transport links and rental demand may have different prospects from a similar property in an area with weaker demand.

    Investors should therefore research the local market before deciding whether a residential opportunity fits their strategy.

    Commercial Property Investment

    Commercial property provides another category of Investment Opportunities.

    Common commercial property types include:

    • Offices
    • Retail units
    • Warehouses
    • Industrial buildings
    • Mixed-use properties
    • Healthcare facilities
    • Hospitality properties

    Commercial property can operate differently from residential property. Lease structures, tenant requirements, vacancy periods and operating costs can all affect the investment.

    Therefore, investors should assess the individual property and its tenant position rather than assuming that every commercial property will provide the same level of income or growth.

    Development and Value-Add Opportunities

    Some investors look for properties where value could potentially be increased through improvements or development.

    These opportunities can include:

    • Refurbishment
    • Property conversion
    • Change of use
    • Planning improvements
    • Extensions
    • New development
    • Improving an underperforming property

    However, these strategies can involve greater risk because costs, planning requirements and project timelines may change.

    A successful investment assessment should consider both the expected value created and the costs and risks involved in creating it.

    Factors to Consider When Assessing Investment Opportunities

    Finding an opportunity is only the beginning. Next, investors need to determine whether the property and financial assumptions make sense.

    Location and Local Demand

    Location remains one of the most important factors in property investment.

    Investors should examine:

    • Rental demand
    • Local employment
    • Transport connections
    • Schools and amenities
    • Population trends
    • New developments
    • Competing properties
    • Local rental values
    • Recent property transactions

    For example, strong tenant demand can support rental income, while improving infrastructure may contribute to the long-term attractiveness of an area.

    Purchase Price and Financing

    The purchase price has a direct impact on potential investment returns.

    Investors should also consider:

    • Mortgage interest
    • Loan-to-value ratio
    • Arrangement fees
    • Refinancing costs
    • Deposit requirements
    • Changes in interest rates

    As borrowing costs increase, highly leveraged investments may experience greater pressure on cash flow.

    For this reason, investors should calculate their expected returns using realistic financing assumptions.

    Taxes and Other Costs

    Tax and transaction costs should also be included when assessing Investment Opportunities.

    Depending on the circumstances, investors may need to consider:

    • Stamp Duty Land Tax
    • Income tax
    • Capital Gains Tax
    • Legal fees
    • Survey costs
    • Mortgage fees
    • Property management costs
    • Maintenance expenses
    • Insurance

    Importantly, tax treatment can depend on the investor’s circumstances, property type and ownership structure. Professional tax advice may therefore be appropriate before making an investment decision.

    Risk and Exit Strategy

    Every investment carries some level of risk.

    Potential property investment risks include:

    • Falling property values
    • Higher borrowing costs
    • Vacancy periods
    • Unexpected renovation costs
    • Lower rental income
    • Changes in regulation
    • Delays in development
    • Difficulty selling the property

    At the same time, investors should consider how they intend to exit the investment.

    An exit strategy could involve selling the property, refinancing it, retaining it for rental income or selling a completed development.

    How Economic Conditions Affect Investment Opportunities

    Economic conditions can influence property markets in several ways. As a result, investors should pay attention to major economic indicators when assessing potential investments.

    Interest Rates

    Interest rates affect the cost of borrowing.

    When mortgage and financing costs increase, investors may experience lower cash flow. Conversely, lower borrowing costs can improve affordability and potentially increase demand.

    However, investors should avoid relying on interest rates alone when evaluating an opportunity.

    Inflation

    Inflation can affect both property income and investment costs.

    For instance, refurbishment, maintenance and construction costs may increase during periods of higher inflation.

    Meanwhile, rental income and property prices may respond differently depending on local demand and market conditions.

    Employment and Economic Growth

    Employment and economic activity can influence demand for both residential and commercial property.

    Areas with growing employment may attract more residents, which can support housing demand. Similarly, strong local business activity can support demand for commercial space.

    Consumer and Investor Confidence

    Market confidence can also affect property transactions.

    When confidence is strong, investors may be more willing to purchase property. On the other hand, periods of uncertainty can make investors more cautious and increase the importance of income, affordability and risk management.

    How to Evaluate Investment Opportunities in the UK

    A structured approach can help investors assess opportunities without becoming overly focused on headline returns.

    First, identify your investment objective.

    An investor looking for regular income may prioritise rental yield and cash flow. In contrast, someone focused on long-term growth may place greater emphasis on location, development potential and future demand.

    Next, review the financial numbers.

    Calculate expected income and account for realistic costs, including:

    • Financing
    • Management
    • Maintenance
    • Insurance
    • Taxes
    • Refurbishment
    • Professional fees
    • Potential void periods

    Then, stress-test the investment.

    Consider what would happen if the property took longer to let, refurbishment costs increased, interest rates rose or the eventual sale price was lower than expected.

    Finally, consider whether the investment still makes sense under less favourable conditions.

    This approach can provide a more realistic view of potential returns and help investors understand the downside before committing capital.

    Finding Investment Opportunities Through Sylvest

    Finding suitable property opportunities can be one of the biggest challenges for investors, particularly those who do not have an extensive property network.

    Sylvest provides a platform designed to connect property investors with deal sourcers and provide access to property opportunities.

    For investors, this creates another route to discovering potential property investments, including opportunities that may not be widely available through traditional property portals.

    Investors can review the available information, decide whether a property fits their strategy and then carry out their own due diligence before proceeding.

    In this way, Sylvest aims to make the connection between deal sourcers and property investors more structured and accessible.

    The platform does not remove the need for due diligence. Instead, it provides investors with another way to discover and assess potential opportunities.

    The Bottom Line

    There are many Investment Opportunities available in the UK property market, from residential and commercial property to development and value-add projects.

    However, the right opportunity depends on the investor’s objectives, available capital, risk tolerance and investment timeframe.

    Ultimately, investors should look beyond projected returns and consider the property’s location, demand, purchase price, financing, costs, taxes, risks and exit strategy.

    Technology and property investment platforms can make opportunities easier to discover and information easier to organise. Nevertheless, proper research and due diligence remain essential before making an investment decision.

    For investors looking to discover property opportunities and connect with deal sourcers, Sylvest provides a structured platform for exploring potential investments.

    Frequently Asked Questions

    What are Investment Opportunities?

    Investment Opportunities are assets, projects or businesses where an investor commits capital with the expectation of generating a future financial return. In property, these can include residential properties, commercial buildings, HMOs and development projects.

    What are the main property Investment Opportunities in the UK?

    The main opportunities include buy-to-let properties, HMOs, student accommodation, commercial property, refurbishment projects, development opportunities and other value-add investments.

    Is property investment a good opportunity in the UK?

    Property investment can provide potential rental income and capital growth, but returns are not guaranteed. Therefore, investors should assess the property’s location, price, demand, costs and risks before investing.

    How do interest rates affect property Investment Opportunities?

    Interest rates influence the cost of borrowing. As a result, higher interest rates can increase financing costs and reduce cash flow, particularly for investments that rely heavily on borrowed money.

    What should I consider before investing in UK property?

    Consider the purchase price, rental demand, expected income, financing costs, taxes, renovation requirements, local market conditions, potential risks and exit strategy.

    Where can I find property Investment Opportunities in the UK?

    Investors can find opportunities through estate agents, property networks, direct approaches, deal sourcers and specialist property investment platforms such as Sylvest.